
Podcast
“Sovereignty Means Being Able to Change Course” – A Conversation with Manfred Beckers
Digital sovereignty in finance: Manfred Beckers discusses cloud dependencies, DORA, exit strategies and maintaining the ability to adapt.
Compliance

08.01.2025|

Implementing the Instant Payment Regulation presents significant challenges for banks and PSPs – particularly with regard to sanctions screening.
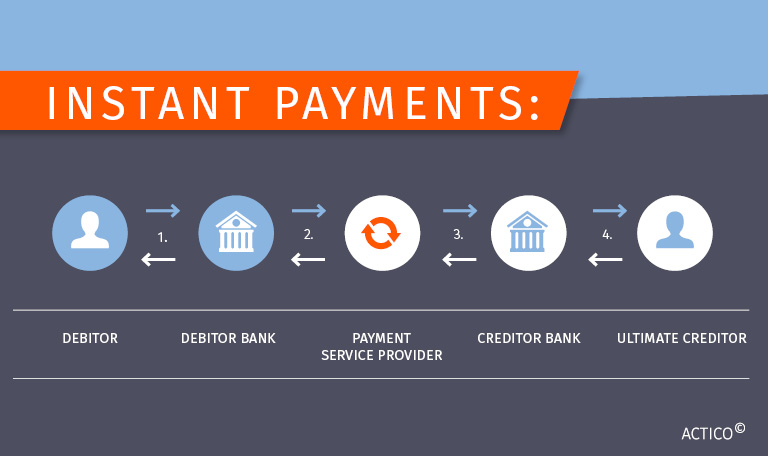
Instant payments, also known as SEPA instant credit transfers (SCT Inst), are Euro transfers within the 34 countries of the Single Euro Payments Area. These transactions enable the transfer of funds within 10 seconds – anytime, around the clock and 365 days a year. While instant payments are processed within ten seconds, standard transfers can take one or more days to complete.
Payment service providers in the EU and beyond are now required to execute instant payments. However, determining how these transactions should be screened against sanctions lists is not always straightforward.
To meet the needs of bank customers who have to make funds immediately available to recipients, many banks offer instant payments, but only some of them extend the scope to include incoming payments too.
Payment service providers such as banks, which provide standard credit transfers in euros, are required to offer the service of sending and receiving instant payments in euros.
The charges must not be higher than the charges that apply for standard credit transfers.
Under the new rules, PSPs need to verify that the beneficiary’s IBAN and name match in order to alert the payer to possible mistakes or fraud before a transaction is made.
PSPs should periodically, and at least daily, verify whether their Payment Service Users (PSUs) are persons or entities subject to targeted financial restrictive measures, and should no longer apply transaction-based screening in that specific context.
The critical importance of robust customer screening in the era of Instant Payments: Discover more here
The obligation of PSPs to periodically verify their PSUs is related only to persons or entities subject to targeted financial restrictive measures. Other types of restrictive measures adopted in accordance with Article 215 TFEU (Treaty on the Functioning of the European Union) or restrictive measures that are not adopted in accordance with Article 215 TFEU fall outside the scope of that obligation. The obligation of PSPs to periodically verify whether their PSUs are persons or entities subject to targeted financial restrictive measures does not interfere with actions that PSPs should be able to take to comply with EU law on the prevention of money laundering and terrorist financing.
Financial institutions operating in multiple countries or regions, decide which payments to examine depending on the regulatory context and their risk appetite. Relevant factors here include the type of payment (domestic vs. international), unusual patterns (e.g. pass-through transactions), transaction value and the payment’s origin/destination (e.g. country/region, recipient type).
Transaction based screening has to be conducted before the payment is executed. But since sanctions lists screening comprises just one part of the payment process, only a limited timeframe – between 500 milliseconds and one second – is available. A window this tight requires efficient IT infrastructure and bringing all available technical solutions into play, such as interface adjustments, storage of hits and clarifications, cache optimisation and workflow and GUI adaptations.
Instant payments align seamlessly with banks’ digitisation strategies. However, they bring heightened risks, requiring IT systems capable of split-second decision-making and meticulous preparation. Customer screening and reducing false positives are now more critical than ever.
Banks having rolled out instant payment projects report needing a lead time of around half a year for analyses, bringing various areas on board and clarifying IT infrastructure.
Execution of a real-time transfer requires payment service providers (PSPs) adhering to the same rules, practices, and standards (“Scheme”) to be present on both sides of the transaction. In 2017, the European Payment Council introduced the Single Credit Transfer (SCTInst) Scheme for Euro instant payments within SEPA. Broad participation by PSPs in this scheme is an essential prerequisite for the wide availability of Euro instant payments throughout the EU.
The payments regulator in Switzerland, the Swiss National Bank, has created an obligation for financial institutions to participate in IP:
During the initial phase, the limit is CHF 20.000,–
Swiss instant payments went live on 20 August, 2024, meaning that individuals and companies can initiate account-to-account transactions. Swiss banks are not obligated to offer outgoing instant payments. Unlike the EU regulation, the Swiss regulation does not impose equivalent charges for standard transfers and instant payments.
The Swiss Interbank Clearing (SIC) payment system, operated by SIX on behalf of the Swiss National Bank, connects bank accounts. Technically, SIC is capable of processing real-time payments. However, to make Instant Payments work across the entire payment chain, adjustments are needed in both the operation and organisation of interfaces between banks and SIX. With the launch of the fifth generation of SIC at the end of 2023, SIX laid the foundation for instant payments, similar to the European SEPA Instant Credit Transfer standard.
In March 2024 the EU published a regulation that makes instant payments fully available in euros to consumers and businesses in the EU and EEA countries. The new rules came into force on 9 January 9 2025 for incoming IP. Sending instant payments will be mandatory by 9 October 2025.
The Swiss National Bank wants to do all that is needed for instant payment to become the new normal in Switzerland. This required the expansion of the technical infrastructure and the participation of the banks in the new process. Since August 20, 2024, Swiss banks are able to receive instant payments from other Swiss banks. Smaller banks which process less than 500,000 transfers per year have until the end of 2026 to get set up.
For bank-PSPs in non-eurozone member states, the deadline for receiving instant payments is 9 January 2027, sending instant payments 9 July 2027.
Customer screening has taken on new urgency with instant payments. Daily checks of customer data against sanctions lists bring unique challenges. Explore the key challenges banks are tackling in this article.
You may also be interested in:
Podcast
“Sovereignty Means Being Able to Change Course” – A Conversation with Manfred Beckers
Digital sovereignty in finance: Manfred Beckers discusses cloud dependencies, DORA, exit strategies and maintaining the ability to adapt.
Compliance

News
Chartis Research Again Names ACTICO a Category Leader for AML Transaction Monitoring 2026
ACTICO has again been named a Category Leader in the Chartis RiskTech Quadrant® for AML Transaction Monitoring Solutions 2026. The assessment recognizes ACTICO’s strengths in risk typology modeling, analytical modeling, model validation, workflow automation, and AI-powered compliance.
Anti-Money Laundering
Financial Institutions/FinTech, Insurance
Awards & Recognitions
News
ACTICO announces it has joined forces with Axe Finance, a global provider of credit and risk management software
ACTICO announces that it has joined forces with Axe Finance, a UK-based provider of credit and risk management software. The deal is supported by Keensight Capital, one of the leading private equity managers dedicated to pan-European Growth Buyout investments.

Webinar
Update on AML Requirements for Insurers: what you need to do now to be ready by July 2027.
AML update for insurers: What needs to be done by July 2027 regarding KYC, risk assessment and transaction monitoring? Including practical insights. Watch the webinar.
Anti-Money Laundering
Insurance
Newsletter
Regular News and Updates
Decision Management Platform
Compliance
Resources
You are currently viewing a placeholder content from Hubspot Embedded Content. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationYou are currently viewing a placeholder content from HubSpot. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationYou are currently viewing a placeholder content from Hubspot Meetings. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationYou are currently viewing a placeholder content from Wistia. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More Information